Spread betting is tax free in the UK for most retail traders: profits carry no Capital Gains Tax and no Stamp Duty, and you do not report them to HMRC. Two conditions attach. HMRC can tax you where the betting is part of a trade you already carry on, and spread betting losses cannot be set against Capital Gains Tax on anything else.
These are the 2026/27 rules, checked on 26 August 2026.
Spread bet or CFD: what you keep after tax
Capital Gains Tax on the same profit, 2026/27 rates
On a £5,000 winning trade, a spread bettor keeps £5,000. A basic-rate CFD trader with the £3,000 exemption unused pays £360 CGT and keeps £4,640.
A spread bet saves £360 in tax on this trade: the Capital Gains Tax the same position pays as a CFD at the basic rate, with the 2026/27 £3,000 annual exempt amount unused. The saving runs one way, because a CFD loss is an allowable loss and a spread bet loss is not (the second condition).
Spread Bet
Gross profit£5,000
Stamp dutyNone
Capital Gains TaxNot chargeable
Kept£5,000
CFD
Gross profit£5,000
Annual exempt amount− £3,000
Taxable gain£2,000
CGT at 18%£360
Kept£4,640
Tax treatment depends on your circumstances and can change. This applies the published 2026/27 figures and is not advice.
The £3,000 annual exempt amount is a whole-year allowance, not a per-trade one. The comparison assumes the whole gain falls inside the chosen tax band. HMRC CG56100 says all debits and credits to a CFD account, including commission and sums equivalent to interest, are brought into the CFD's gain or loss, so the tool shows the CFD's tax before those costs. Rates and allowance: HMRC, 2026/27. HMRC's Capital Gains Manual (CG56105) states that no chargeable gains or allowable losses arise from spread betting. For most UK retail traders, profits are therefore free of Capital Gains Tax. Tax treatment depends on individual circumstances and can change.
Our spread bet content is supported by broker partners, who pay us on a retainer basis rather than per referral.
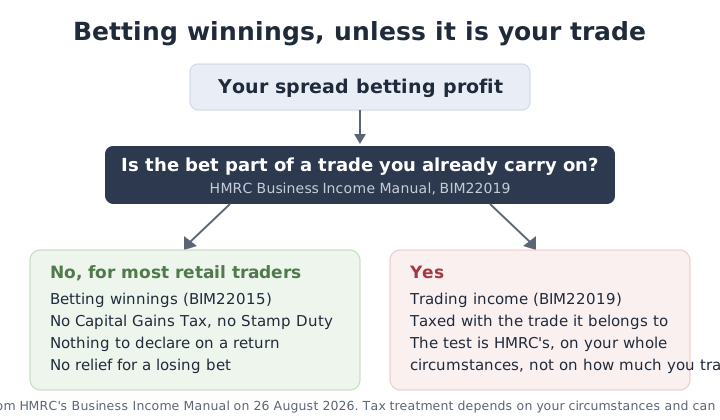
The chart turns on one question, whether the bet is part of a trade you already carry on. For most UK retail traders it is not, so the profit sits outside Capital Gains Tax (CG56105); a yes means trading income, taxed with that trade (BIM22019). Tax treatment depends on your individual circumstances and can change.
Enter your gross profit, your tax band, Basic 18% or Higher 24%, and whether the £3,000 allowance is unused or already used. The tool shows what you keep as a spread bettor and as a CFD trader after Capital Gains Tax. It needs no sign-up.
For most UK retail traders, spread betting profits sit outside Capital Gains Tax under HMRC’s Capital Gains Manual page CG56105. According to HMRC’s Business Income Manual page BIM22020, whether a particular spread bet is taxable depends on the terms of the contract and what is actually done. Tax treatment depends on your individual circumstances and can change, so you should seek professional tax advice if you are unsure.
No Capital Gains Tax. You do not pay Capital Gains Tax on a spread betting profit.
No Stamp Duty. No Stamp Duty is charged on a spread bet, because you never own the asset.
No Self Assessment reporting. You do not report spread betting profits on a Self Assessment return.
No loss relief. Losses cannot be set against other capital gains.
One exception applies. Profits that form part of a trade you already carry on are taxed as trading income (BIM22019).
In brief, the Spread Bet UK home page gives the same tax position alongside the FCA authorisation rule and the leverage caps, and links this tax guide.
The tool works on the profit a spread bet makes, points moved times the stake per point, and our guide is where we have spread betting explained with worked examples.
The Two Conditions On Tax-Free Status
The exemption is the rule, not a loophole, but it is conditional in two ways that matter before you rely on it.
1. It Must Not Be Your Trade
HMRC's position is set out in its Business Income Manual. BIM22015 states the general rule that the profits of betting and gambling are not the profits of a trade, resting on Graham v Green (1925), in which a man who made his living backing horses was found not to be trading. BIM22017 adds that having a system for placing bets, or being successful enough to live on it, does not make the activity a trade either. BIM22019 is where the exception lives: betting that is an element of a trade you already carry on.
Being full-time, systematic or profitable does not by itself make spread betting a trade. Graham v Green is authority for exactly the opposite. The line BIM22019 draws is that the winnings must arise out of carrying on the trade rather than out of an opportunity the trade presents.
HMRC’s spread betting page, BIM22020, applies that line to spread bets. Whether a bet is taxable depends on the contract’s terms and the economic substance of what is done. A spread bet placed by a limited company is different. CFM50380 treats it as a contract for differences within the Corporation Tax derivative contracts rules, so the company pays Corporation Tax.
2. Losses Carry No Relief
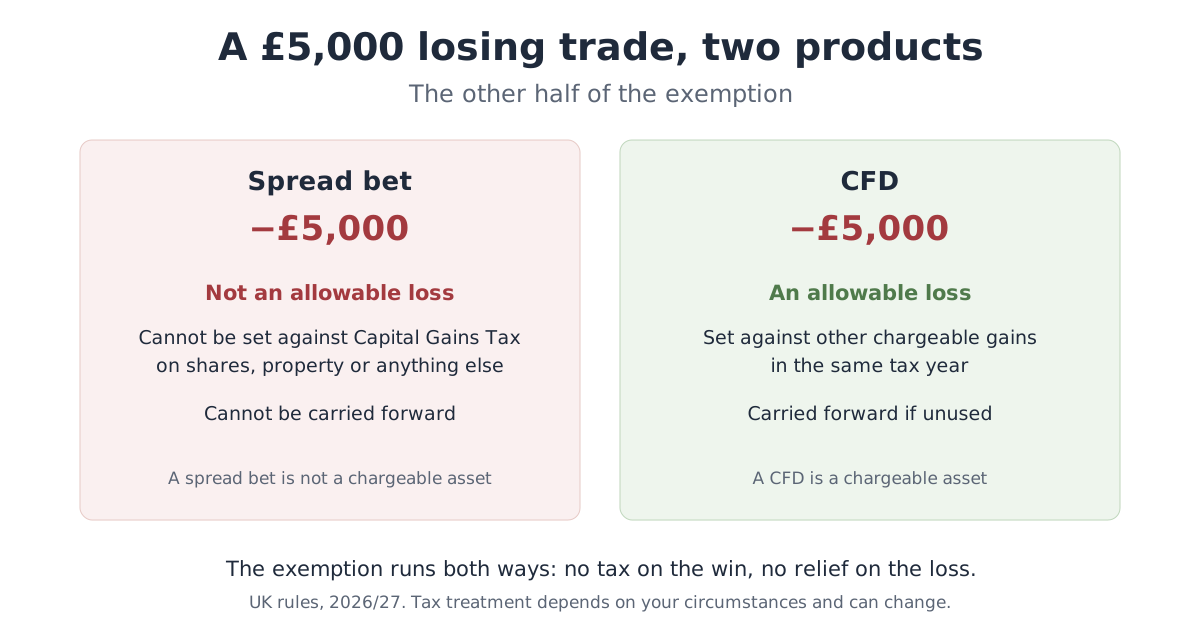
The exemption runs both ways. Because a spread bet is not a chargeable asset, a losing spread bet produces no allowable loss: it cannot be set against Capital Gains Tax on shares, property or anything else, and it cannot be carried forward. A CFD trader who loses can offset; a spread bettor who loses cannot. That is the cost of the exemption, and it is the reason the choice between the two products is not automatic.
The same £5,000 loss, two products. On the spread bet it is not an allowable loss, so it cannot reduce Capital Gains Tax on anything else and cannot be carried forward. On the CFD it can be set against other chargeable gains. The exemption runs both ways.
Capital Gains Tax On Spread Betting And Shares
Tax treatment depends on your individual circumstances and can change, so you should seek professional tax advice if you’re unsure.
Worked Example Comparing Spread Betting With Buying Shares
Suppose you believe a UK-listed company’s share price will rise from £10.00 to £12.00.
Buying shares
If you buy 1,000 shares at £10.00, that is a £10,000 investment. Selling at £12.00 gives you £12,000, earning you a gross profit of £2,000.
You would also pay 0.5% Stamp Duty Reserve Tax (SDRT) when purchasing UK-listed shares, adding £50 to your costs.
The £50 Stamp Duty Reserve Tax is a deductible cost, so the taxable gain is £1,950 rather than £2,000. With the £3,000 allowance already used by other gains, a higher or additional rate taxpayer pays 24% on £1,950, which is £468.
Spread betting
Now let’s say you open an equivalent spread bet on the same price movement and the market rises by the same amount, you generate an equivalent £2,000 profit.
Assuming you are an individual trader, no CGT is generally payable on spread betting profits (depending on your circumstances). Also, because you never take ownership of the underlying shares, you don’t have to pay stamp duty.
Stocks and shares ISA
A spread bet is not on gov.uk’s list of what a stocks and shares ISA includes. Shares bought inside the ISA pay no Capital Gains Tax on the same £2,000 gain. Only money paid in within the £20,000 yearly allowance for 2026/27 goes in, per gov.uk’s ISA guide, read .
The ISA allowance, CGT on gains inside the ISA and whether a spread bet can be held in it, for the 2026/27 tax year.
Stocks and shares ISA
2026/27
ISA allowance
£20,000 per tax year, across all ISAs
Capital Gains Tax on gains inside the ISA
None due on the £2,000 gain
Can a spread bet be held in it?
No, spread bets are not investments a stocks and shares ISA holds
The Same Trade, Taxed Two Ways (2026/27)
The difference is easiest to see on a single position held as a spread bet and as a CFD. Both open long on the UK 100 at 10,850 and close at 11,050, a 200-point move: £25 per point as a spread bet and 25 contracts as a CFD, producing the same £5,000 gross profit either way.
Eleven lines of one £5,000 winning trade, from position and dates through to tax at each rate, held as a spread bet and as a CFD.
On one £5,000 winning trade
Spread bet
CFD
Position
£25 per point
25 contracts
Opened / closed
10,850 → 11,050
10,850 → 11,050
Gross profit
£5,000
£5,000
Stamp Duty
None
None
Capital Gains Tax
Not chargeable
Chargeable
Annual exempt amount applied
Not applicable
£3,000
Taxable gain
£0
£2,000
CGT at the 18% basic rate
£0
£360
CGT at the 24% higher rate
£0
£480
Kept, basic-rate taxpayer
£5,000
£4,640
Kept, higher-rate taxpayer
£5,000
£4,520
The £3,000 annual exempt amount is the 2026/27 figure and it is a whole-year allowance, not a per-trade one: if other gains have already used it, the CFD column's taxable gain is the full £5,000 and the tax is £900 or £1,200 rather than £360 or £480. On the CFD, HMRC’s CG56100 brings commission and sums equivalent to interest into the gain computation. The CFD’s costs therefore reduce its taxable gain, and the table shows the CFD’s tax before those costs. Spreads differ from broker to broker, and we show the spread figure each ranked broker publishes at UK spread betting brokers side by side.
Overnight funding is a daily charge or credit applied to a spread bet held past the broker’s cut-off, set as a rate above or below an interest-rate benchmark (StoneX Trading publishes SONIA plus 3% on long positions, SONIA minus 3% on short positions). Work out the cost for your own position with the overnight funding calculator.
Reverse the trade and the ranking reverses with it. A £5,000 loss costs a spread bettor the full £5,000, while a CFD trader can set the loss against other chargeable gains. Size a position with our spread betting calculator before deciding which side of that trade-off you want to be on.
How Are CFDs And Spread Bets Taxed In The UK?
For most UK retail traders, CFDs and spread bets are taxed differently in the UK. A CFD profit is chargeable to Capital Gains Tax and a spread bet profit is not. HMRC’s CG56100 treats a retail CFD as a financial future charged under the capital gains rules unless the profits are trading income. A CFD loss is an allowable loss. Neither product pays Stamp Duty Reserve Tax. We compare the two products beyond tax at how spread bets and CFDs differ beyond tax.
CGT, claiming losses against CGT, Stamp Duty and dividend tax, compared across spread betting, CFD trading and share trading.
Tax Type
Spread Betting
CFD Trading
Share Trading
Capital Gains Tax (CGT)
0%
18 - 24%* above the £3,000 allowance
18 - 24%* on profits
Claim Losses Against CGT
No
Yes
Yes
Stamp Duty
0%
0%
0.5%
Dividend Tax
0%
No dividend tax, with adjustments part of the gain (CG56100)
10.75% to 39.35%*
*Subject to income tax band.
Why Isn’t Spread Betting Taxed In The UK?
For most UK retail traders, spread betting is not taxed: no asset is bought or sold, so no Capital Gains Tax and no Stamp Duty arise. HMRC’s Capital Gains Manual page CG56105 says "no assets are acquired or disposed of and no chargeable gains or allowable losses arise from spread betting". Under BIM22020, whether a particular spread bet is taxable depends on the contract’s terms and what is actually done. Tax treatment depends on your individual circumstances and can change, so you should seek professional tax advice if you are unsure.
Spread Betting Tax FAQs
Is Spread Betting Taxable At HMRC?
No, for most UK retail traders spread betting is not taxable; CG56105 says "no assets are acquired or disposed of and no chargeable gains or allowable losses arise from spread betting". Whether a particular spread bet is taxable depends, under BIM22020, on the terms of the contract and the economic substance of what is done. Having a system for placing bets, or being successful enough to earn a living from betting, does not on its own make the activity a trade, BIM22017 says. Betting that is part of a trade you already carry on can be taxed, as BIM22019 explains. Tax treatment depends on your individual circumstances and can change, so you should seek professional tax advice if you are unsure.
Is Spread Betting Always Tax-Free?
No. The exemption is the general rule and it carries two limits. BIM22019 sets the first. Betting wins are taxable where they arise from a trade you already carry on, so the same profits can be treated differently depending on what else you do for a living. The second limit runs the other way and costs you rather than HMRC. A spread bet is not a chargeable asset, so a loss on one is not an allowable loss, and it can neither reduce Capital Gains Tax on other gains nor be carried forward. Tax treatment depends on your individual circumstances and can change, so you should seek professional tax advice if you are unsure.
Do I Have To Declare Spread Betting Winnings To HMRC?
No. For most UK retail traders you do not declare spread betting winnings to HMRC. A spread bet produces no chargeable gain under HMRC’s guidance CG56105. gov.uk asks you to report Capital Gains Tax only when your total taxable gains are above your allowance. Winnings that arise from a trade you carry on are trading income under BIM22019. That situation needs professional tax advice.
Is Spread Betting Classed As Gambling?
For regulation, spread betting is a financial product, and the Financial Conduct Authority, not the Gambling Commission, authorises and supervises the firms that offer it. For tax, a profit sits outside Capital Gains Tax for most UK retail traders, because CG56105 says no chargeable gains or allowable losses arise from spread betting. BIM22020 ties any tax to the terms of the contract and the economic substance of what is done. Tax treatment depends on your individual circumstances and can change, so you should seek professional tax advice if you are unsure. Our is spread betting gambling page sets out the distinction point by point.
Can HMRC Tax Me As A Professional?
It is possible, though the test is not how much you trade. Graham v Green establishes that even a full-time, systematic bettor is not thereby trading, and BIM22017 says the same of having a system or earning a living at it. HMRC would need to show the betting arose out of a trade you were already carrying on, under BIM22019. If your circumstances are unusual, take advice rather than assuming either answer.
Are Taxes The Same For Share Trading And Spread Betting?
No. Buying shares outright can attract both Stamp Duty on the purchase and Capital Gains Tax on the profit, because you take ownership. Spread betting shares attracts neither, because the bet is a derivative and no ownership changes hands.
Justin Grossbard co-founded Spread-Bet.co.uk with Noam Korbl in 2024, and co-founded the broker comparison network CompareForexBrokers with him in 2014. He has written for Kiplinger, Entrepreneur, Finance Magnates and MoneyShow since 2022, with articles on forex and trading at MoneyShow, Finance Magnates and Kiplinger.
Updated . Updated on 9 Oct 2026: The summary box under the tax calculator, the main figure’s caption, the answer on why spread betting is not taxed and the two FAQ answers now cite BIM22020 and CG56105 for most UK retail traders instead of saying HMRC treats a spread bet as betting.